


 Be The Investor Research
Reddit's 61% Growth Supports Its Premium, but the Next Quarter Slows

Reddit's second-quarter revenue rose 61% and weekly active uniques reached 514.6 million, supporting a richer valuation than slower-growing peers. Management's third-quarter guide, however, implies a clear deceleration and leaves search traffic as a risk.
Reddit's premium valuation rests on a simple claim: growth is fast enough to justify paying more for each dollar of earnings than investors pay for larger advertising platforms. The company's second-quarter results support part of that case, while its third-quarter outlook shows why the premium is not risk-free.
Revenue reached $804.9 million in the second quarter, up 61% from a year earlier. Weekly active uniques rose 24% to 514.6 million, crossing half a billion, and ad revenue reached $762 million. The original comparison also notes that active advertisers grew more than 70% and revenue from Reddit's scaled channel doubled.
Management guided to third-quarter revenue of $860 million to $870 million. Against the prior-year base, that represents roughly 47% to 49% growth, a meaningful slowdown from 61%. Deceleration from a high rate is not the same as contraction, but it matters when the stock's valuation assumes Reddit will keep outgrowing Meta, Alphabet and other advertising peers.
Profitability is the second test. The source comparison calculated a 28.2% operating margin over the four quarters through June 2026, below Meta's 38.1% but far above Reddit's own 7.9% in the comparable year-earlier period. Those calculations use matched four-quarter windows, which makes them more useful than comparing isolated quarterly margins.
Traffic from search remains a separate risk because Reddit has limited control over referral algorithms. Management described search traffic as volatile and said visibility was low. The next report must show whether direct usage and advertiser growth can offset that variability while margins continue to expand. Reddit has earned a growth premium; the debate is how much of that progress is already reflected in the price.
Continue your META research
Related News
Tesla, Meta and RTX Earnings Put AI Spending and Industrial Demand to the Test
A concentrated earnings calendar will test two market concerns at once: whether heavy AI spending is producing returns and whether industrial and consumer demand can withstand higher financing costs after a bruising week for technology shares.

Big Tech Rebounds, but Earnings Must Justify the AI Spending Cycle
Technology shares recovered ahead of major earnings reports after a sharp weekly decline. Strong early profit growth supports the market, while elevated expectations leave little tolerance for weak guidance.
Marvell’s Google TPU Delay Looks Like Timing Risk, Not Lost Demand
A reported Google TPU delay pressured Marvell shares, yet the chipmaker’s data-center growth and rising quarterly guidance point to a scheduling issue rather than evidence that the program disappeared.
Amazon's AI Upside Now Depends on More Than AWS Growth
Morgan Stanley's $350 Amazon target combines faster AWS growth with robotics savings, Bedrock adoption and AI shopping. The range of assumptions explains both the upside case and the risk in today's valuation.
Apple Tightens App Store Rules on AI Nudification and Hidden Features
Apple explicitly expanded its App Store rules to cover nonconsensual AI imagery and bait-and-switch apps. The policy strengthens enforcement language after pressure over nudification tools, but implementation remains the key test.

Disney's Character.AI Deal Separates Talent and Technology From Liability
Disney hired most Character.AI employees and became the opening bidder for a broad technology license, while the bankrupt company retains legal claims. Court approval and competing bids still stand between the structure and completion.
Earnings Week Tests Credit, AI Spending and the Consumer

The week of October 19 shifts attention from macro data to company execution. Capital One, Meta, Tesla, Netflix and a broad group of industrial, semiconductor, airline and consumer companies report while the economic calendar is relatively light.
Capital One will test consumer credit, funding spreads and Discover integration. Meta will put AI engagement against capital spending. Other reports make those events more informative: airlines and American Express can show whether consumers are absorbing higher fuel and borrowing costs, while Lam Research, Texas Instruments and Western Digital can reveal whether AI infrastructure demand is broadening.
The backdrop raises the standard for a positive reaction. The source report noted that some banks sold off despite headline beats as investors focused on margins, expenses and credit. Higher bond yields reduce the present value of future earnings, while hot inflation can keep the Fed restrictive.
This is more than an earnings calendar. The week provides connected tests of household resilience, AI monetization and industrial demand. Investors should compare credit losses, capital budgets and order trends across companies before drawing a broad conclusion from any single stock move.
Anthropic Pledges 5% of Its Shares to a Public Benefit Fund

Anthropic plans to commit 5% of its shares to a new public benefit fund, an unusually large equity pledge whose economic value will rise or fall with the private company's valuation.
The commitment is subject to stockholder approval. Anthropic said its board may add another 2% for every 50% increase in the company's value above a defined baseline. The structure links the fund's potential resources directly to corporate growth rather than promising a fixed cash amount.
Anthropic said the fund could support traditional nonprofits or direct distributions to specific populations. That mandate is broader than the safety research, biomedical work and nonprofit discounts the company already conducts inside its public benefit corporation.
Important questions remain unanswered. Anthropic has not yet published the valuation baseline, the fund's governance, voting rights, liquidity arrangements, grant process or the circumstances under which the board would exercise its discretion to add shares. The company said it would provide more detail in the coming months.
The distinction between committing shares and donating cash matters. Private-company stock is illiquid, its value can change sharply between financing rounds, and converting it into grants may depend on a sale, tender offer, public listing or other liquidity event. Dilution from future financing could also affect the fund's percentage unless the structure protects it.
The announcement creates a measurable starting commitment, but the public-benefit outcome cannot yet be assessed from the 5% headline alone. Governance documents and evidence of funded programs will show whether the structure becomes an independent source of capital or remains closely controlled by the company.
Trump Media and Rumble Fell Faster Than the Market as Merger Risk Loomed
Trump Media fell 6% and Rumble dropped 8% during an October 16 market selloff, compared with a 1.4% decline in the S&P 500 proxy cited by the source. The gap is consistent with both stocks' smaller size and high sensitivity to changes in risk appetite, but the companies have different fundamental catalysts.
Trump Media's central event is its proposed all-stock merger with TAE Technologies. A September 30 SEC registration statement advances the approval process but remains preliminary. The filing says roughly 292.6 million new Trump Media shares are expected to be issued to TAE stakeholders based on then-current awards and warrants.
That share issuance would transform the company. TAE develops fusion energy, power management and cancer-therapy technology, while Trump Media operates Truth Social, streaming and financial brands. The merger could provide capital for TAE's development, but commercial fusion remains unproven and the transaction still requires approvals and completion conditions.
Rumble's exposure is more conventional. Its revenue depends on advertising, subscriptions, licensing and creator activity. A market selloff can pressure the shares, but its operating test is whether users, monetization and cash generation improve.
The one-day declines do not prove either business deteriorated that afternoon. They show how quickly valuation risk can surface when investors retreat from speculative equities. For DJT holders, the decisive evidence is the final merger terms, shareholder approval and the combined company's financing plan.
Carnival's Record 2027 Bookings Shift Attention to Pricing
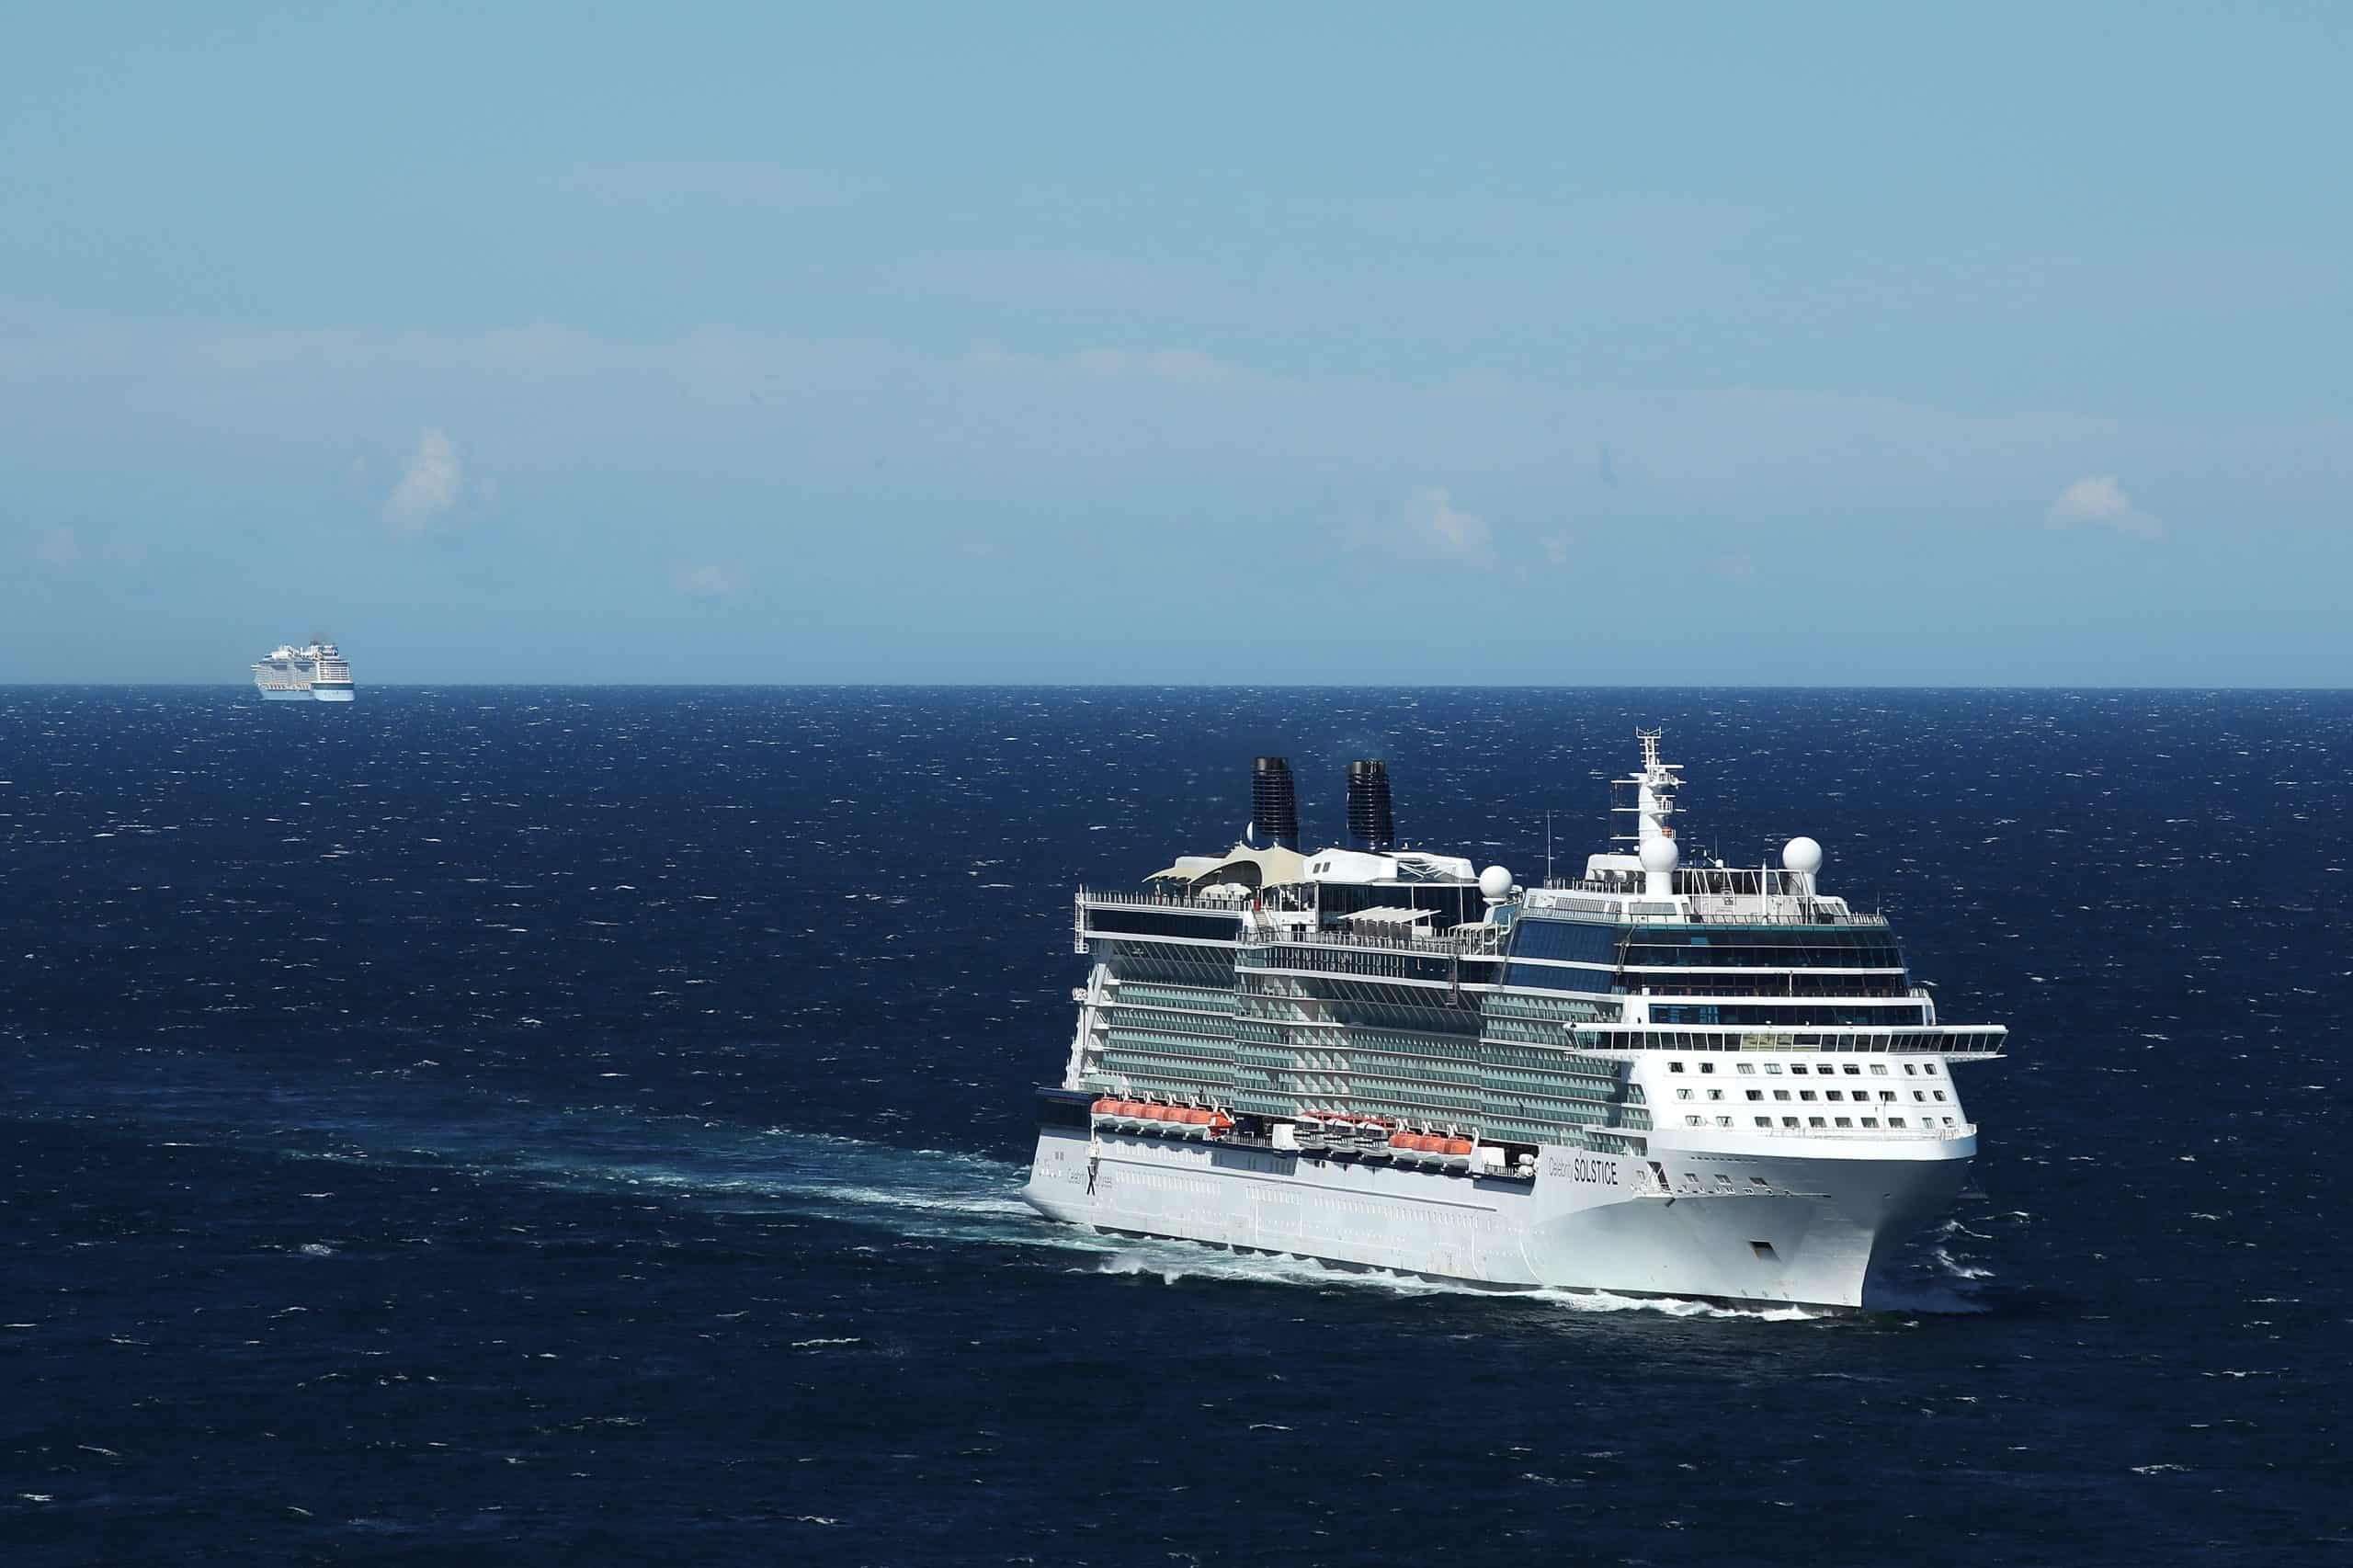
Carnival's shares gained sharply after the cruise operator reported record booked occupancy and pricing for 2027. The advance outpaced Royal Caribbean and Norwegian Cruise Line over the cited month, suggesting investors reacted to company-specific booking strength rather than only a broad travel rally.
Carnival's September 29 earnings release said both booked occupancy and pricing for full-year 2027 were at record levels. Because cabins are sold well before sailing, that booking curve provides useful revenue visibility. It does not guarantee the revenue will be realized at the same economics, since cancellations, itinerary changes, onboard spending and discounting can alter the outcome.
The company also needs to convert demand into yield growth after fuel, labor and financing costs. Fuel prices can move quickly, while cruise capacity is costly to reposition. Strong advance bookings give Carnival more room to protect pricing, but investors still need evidence in reported net yields and operating margins.
The stock's rebound does not erase balance-sheet risk or the possibility that expectations have moved ahead of results. Carnival still carries substantial debt accumulated during the pandemic era. Higher cash generation can improve that position, but interest expense and refinancing terms remain part of the equity case.
The booking report supports a constructive demand view, not an automatic instruction to chase the rally. The next decisive evidence will be 2027 realized pricing, net yields and debt reduction. If those measures confirm the booking curve, the recent outperformance has an operating foundation. If discounting rises, the record headline will prove less valuable.
CoreWeave Credit Insurance Tops 1,000 Basis Points as Debt Fears Rise

CoreWeave's equity sell-off is being reinforced by a harsher signal from the credit market. Five-year credit-default swaps on the AI infrastructure provider moved above 1,000 basis points, while a bond due in 2031 yielded about 14.5% on October 16 after nearly reaching 16%.
A credit-default swap is insurance against a borrower's failure to repay. At a quote of 1,000 basis points, insuring $1 million of debt costs more than $100,000 a year before contract details. CNBC, citing Bloomberg pricing, said the market implied roughly a 60% probability of default within five years. That is a model-based market estimate, not a prediction that default will occur.
The bond comparison shows how sharply financing conditions changed. The 2031 security was issued in April at a 9.75% yield. A jump to 14.5% means investors demand substantially more compensation to hold the same debt, which can make future borrowing or refinancing more expensive. CoreWeave shares fell about 25% over the week as the credit move accelerated.
The counterevidence is substantial demand. CoreWeave reported record second-quarter revenue and backlog, and later said it added more than $25 billion of net new customer commitments early in the third quarter. Nvidia Chief Executive Jensen Huang also said the company's financial position was stable and improving. Customer commitments support future revenue, but they do not eliminate the timing mismatch between heavy upfront construction costs and cash collected over long contracts.
For equity investors, the central issue is not whether a default happens tomorrow. It is whether CoreWeave can fund capacity, service debt and preserve value for shareholders while its cost of capital is elevated. The next earnings report should be judged on cash flow, debt maturities, collateral requirements and customer concentration, not backlog alone.
Latest comments