
Visa and Mastercard Move Stablecoin Payments Into Commercial Use
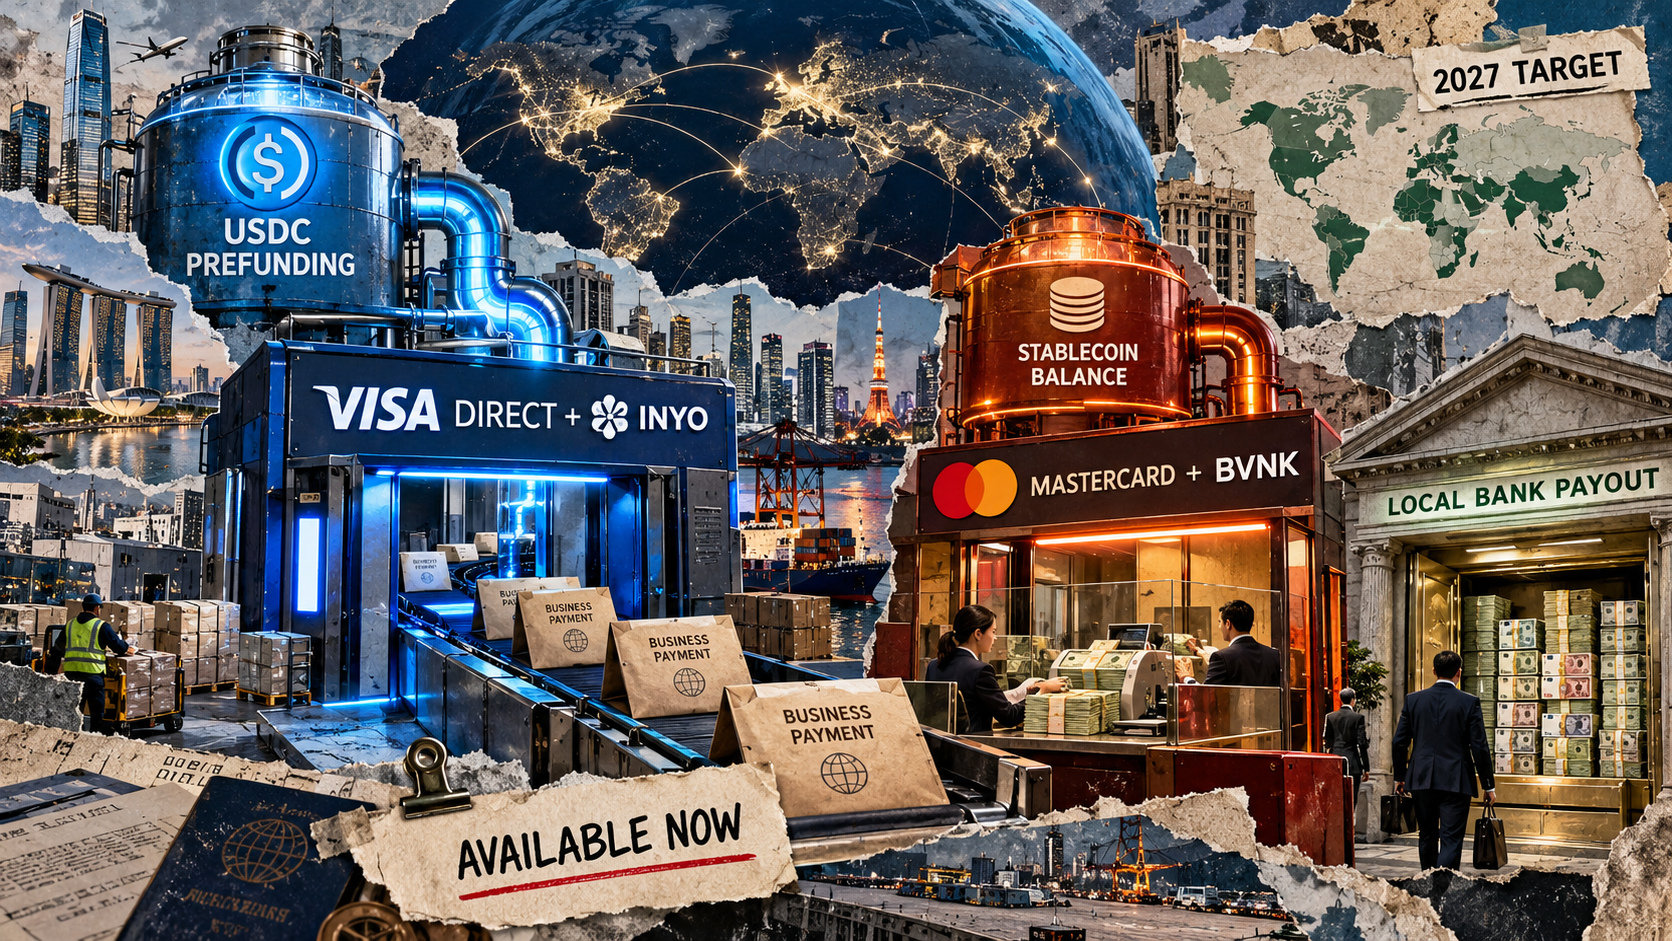
Visa put USDC prefunding into production with Inyo, while Mastercard launched a multi-money platform with BVNK, moving stablecoins closer to ordinary treasury and payout workflows.
Visa and Mastercard are moving stablecoin services from experiments into commercial payment infrastructure, but their new offerings solve different parts of the money-movement process.
Visa said Inyo Global became the first provider to put Visa Direct's stablecoin prefunding capability into production. Eligible businesses can fund cross-border payout obligations with USDC in near real time instead of relying only on traditional banking windows. The recipient can still receive local currency through Visa Direct, so the stablecoin is primarily a treasury and settlement tool on the sender's side.
Mastercard, meanwhile, launched its Global Money Platform with BVNK. The product combines fiat and stablecoin accounts, conversion, card functions and local bank payouts through one application programming interface. Nuvei, Marqeta, Ontop, Beem and Almond FinTech were named among early integrators. Mastercard acquired BVNK in August 2026, making the platform the first major integration announced after that deal.
The business case is less about replacing cards than reducing funding friction. Cross-border payment companies often maintain balances across multiple banks, currencies and time zones. Stablecoin prefunding can extend operating hours and reduce idle cash if compliance, liquidity and redemption remain reliable. Mastercard's account model goes further by letting businesses hold and convert conventional money and stablecoins within one system.
Important limits remain. Visa described access for eligible clients, not universal availability, and neither company disclosed expected transaction volume, fees or revenue contribution. Mastercard said its platform can support local payouts across many markets, but that is not the same as every stablecoin service being available in every country. Regulatory permissions, bank relationships and customer checks still govern deployment.
For Visa and Mastercard investors, the announcements show both networks adapting their existing distribution and compliance advantages to digital dollars. They do not yet establish a material earnings catalyst. The more revealing measure will be whether stablecoin funding attracts new payment volume or mainly changes the back-end asset used to settle transactions already flowing through the networks.
Latest comments