
Host Hotels Has the Safer Dividend Cushion, While Vail Bets on a Snow Rebound
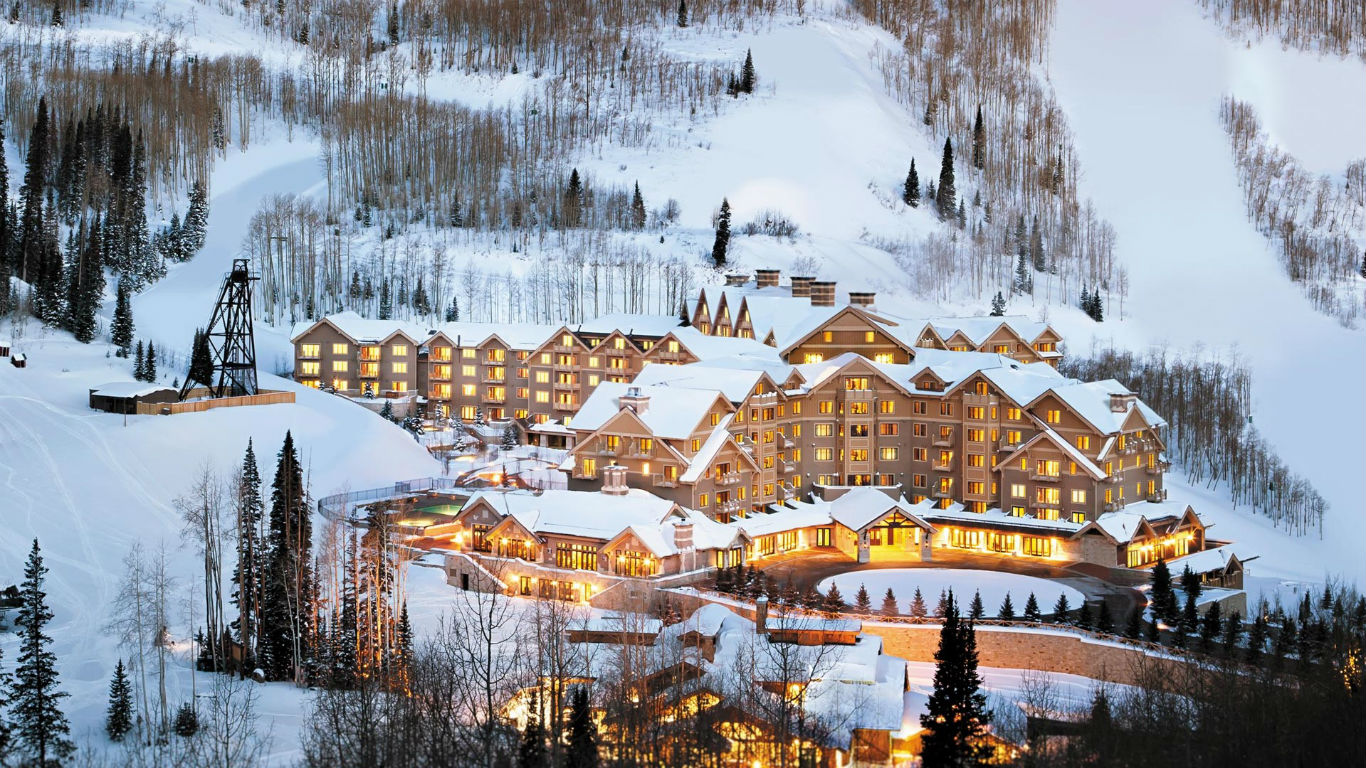
Vail Resorts offers the higher yield but paid more than annual earnings after a weak snow season. Host Hotels combines lower leverage with stronger payout coverage and diversified demand.
Vail Resorts and Host Hotels both depend on travel spending, but their dividends carry very different risks. Vail offers the higher yield and direct upside to a better ski season. Host provides a lower regular yield with stronger coverage, less leverage and broader demand across hotels and resorts.
Vail's fiscal 2026 was shaped by one of the weakest western U.S. snow seasons in decades. Visitation fell sharply even as pass revenue held up better, showing the value of selling Epic Passes before weather is known. The same fixed-cost structure that protects advance cash flow also makes poor attendance painful for ski-school, rental, dining and lift-ticket revenue.
Vail paid $8.88 per share annually in the source comparison, more than twice fiscal earnings per share of $4.12. Management points to free cash flow rather than net income as the coverage measure, but the gap still leaves less room for another weak season. The company also carries higher leverage than Host.
Host's second-quarter results were more supportive. Comparable hotel revenue per available room rose 7% to $251.53, helped by higher room rates, leisure demand, group business and World Cup traffic. The company raised its 2026 RevPAR growth guidance to 4.75% to 5.25%. Its regular dividend used a much smaller share of adjusted funds from operations in the source analysis.
Host is not risk-free. Hotel demand can weaken in a recession, and World Cup benefits are temporary. Yet its portfolio spans multiple markets and customer types, while its investment-grade balance sheet provides more flexibility. Vail is more concentrated in destination skiing and weather-sensitive spending.
Income investors should distinguish Vail's attractive headline yield from the durability of the payout. A normal snow year and stronger visitation could improve coverage quickly, but another poor winter would test it. Host's lower yield comes with the better current buffer, making it the more defensive choice until Vail demonstrates that visitation and free cash flow have recovered.
Latest comments