



Deere and Caterpillar Have Crushed Industrials in 2026 — Here’s What Investors Should Watch Before Taking Profits
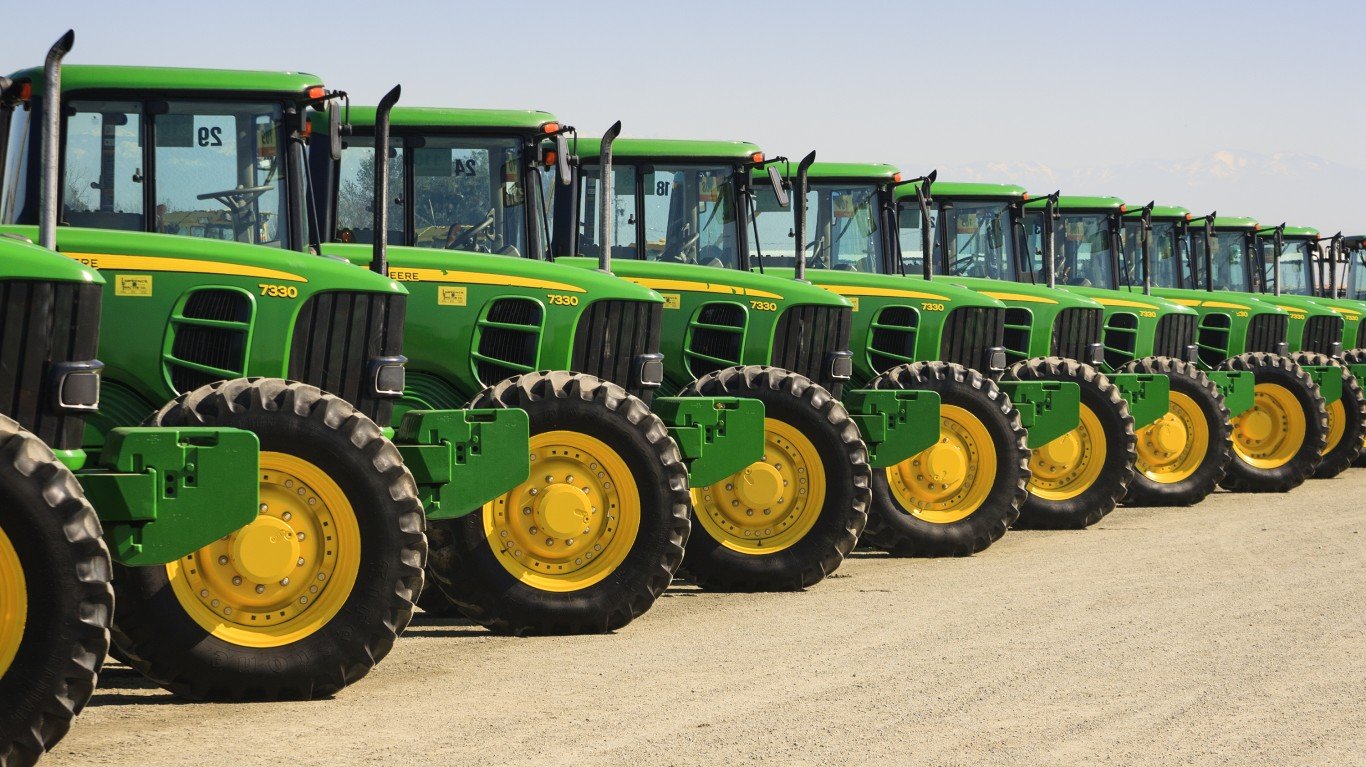
Deere and Caterpillar have materially outperformed the broader industrial sector in 2026. Their rallies are supported by company-specific fundamentals, but the gap versus peers raises the importance of valuation, backlog quality and position sizing.
Deere and Caterpillar have separated sharply from the broader industrial sector in 2026, creating a familiar problem for investors: strong businesses can remain strong for longer than expected, but large relative gains also raise the cost of being wrong.
The supplied market snapshot showed Deere up roughly 47% year to date and Caterpillar about 44%, compared with gains near 12% for both the Industrial Select Sector SPDR Fund and the S&P 500. Paccar, another major industrial name, had risen closer to the sector average. That dispersion suggests the rally in Deere and Caterpillar was not simply a broad industrial re-rating.
The fundamental backdrop supports at least part of the move. Caterpillar reported second-quarter sales and revenues of $20.5 billion, up 24% year over year, marking the first quarter in company history above $20 billion. Management highlighted broadening momentum and growing backlog, while power-generation demand tied to data centers has become an important growth engine.
Deere’s latest quarter also showed resilience. The company reported third-quarter 2026 net income of $1.379 billion, or $5.10 per share, and worldwide net sales and revenues of $12.608 billion, up 5% from a year earlier. Deere also raised its full-year net-income guidance to $4.75 billion to $5.00 billion and said order-book trends reinforced its view that 2026 could mark the bottom of the agricultural equipment cycle.
Those facts explain why the two stocks can outperform even when the sector does not. Caterpillar has exposure to construction, mining, energy and AI-related power infrastructure. Deere is positioned for an eventual recovery in large agricultural equipment after a difficult farm-machinery cycle. Their earnings drivers are different from many industrial peers, which makes simple sector-relative analysis incomplete.
The case for taking some profits is mostly about asymmetry. When a stock has already gained more than 40% in less than a year, the market has usually incorporated a substantial amount of future improvement. A disappointing order trend, weaker margin outlook or slower end-market recovery can therefore produce a larger share-price reaction than it would have at a lower valuation. That is especially relevant for investors whose positions have grown well beyond their intended portfolio weight.
The case for holding is equally straightforward. Neither company’s operating thesis has obviously broken. Caterpillar’s record results and backlog indicate that demand remains strong, while Deere’s improved guidance and order-book commentary point to stabilization rather than deterioration. Selling solely because a stock has risen can be as undisciplined as buying solely because momentum is strong.
The better framework is position sizing. An investor who originally targeted a 5% portfolio weight and now owns 9% because of price appreciation faces a different decision from an investor considering a new position. Trimming back toward a target allocation can reduce single-stock risk without abandoning the underlying thesis.
For Caterpillar, the next major test is whether data-center and energy orders stay strong as additional manufacturing capacity comes online. For Deere, the key variables are agricultural equipment demand, order books and whether the company’s view of a cyclical bottom is confirmed by customer behavior. Both companies also need to protect margins as volumes and product mix change.
The sector comparison remains useful, but only as context. If the broader industrial group begins to outperform while Deere and Caterpillar stop participating, that could indicate their company-specific re-rating has matured. If the leaders continue to deliver better earnings and order trends than peers, continued relative strength would be easier to justify.
A useful cross-check is the cycle each company is actually selling into. Deere’s third-quarter presentation still forecast U.S. and Canadian large-ag equipment demand down 15% to 20% for fiscal 2026, while management simultaneously improved company-level net-income guidance. That combination suggests Deere’s stock strength is partly a recovery trade built on expectations that the agricultural cycle is bottoming before reported industry volumes fully recover. Caterpillar is in a different phase: its recent growth is being supported by strong current demand in Power & Energy, construction and resource markets. Investors should therefore avoid treating the two rallies as one identical macro trade.
BTI’s bottom line: Deere and Caterpillar have earned much of their 2026 outperformance through company-specific execution, not simply sector momentum. Existing holders should focus on position size and the durability of the earnings drivers rather than making an all-or-nothing decision based on the size of the gains.
Continue your DE research
Related News
BitMine’s Ether Hoard Reaches 4.95% of Supply
BitMine added 10,452 Ether and now holds 6.05 million tokens, or 4.95% of supply. Its staking income, buybacks and exposure to Ether prices matter more as the company nears its 5% accumulation target.
BlackRock's Bitcoin Transfer Looks Like Settlement, Not a New Sell Signal
Wallets labeled as BlackRock-linked sent about $262 million of bitcoin to Coinbase Prime after a large ETF outflow. The close match suggests redemption settlement, though public data cannot prove a one-to-one link.
Initia Halted Its Network After a Bridge Exploit Drained Reserves
A MoveVM script-caching flaw let an attacker create unauthorized bridge claims, forcing Initia to halt its network. The incident left ordinary withdrawals failing and restart details unresolved.
Lido Opens 2,048 ETH Validators With a 32 ETH Operator Bond
Lido's new Community Staking Module lets permissionless operators run validators with balances up to 2,048 ETH. The capital efficiency is real, but activation queues and stake caps limit immediate scale.
Moderna's Melanoma Vaccine Worked, but Expectations Were Higher
Phase 3 data showed significant reductions in melanoma recurrence and distant spread, yet Moderna fell as investors weighed a smaller benefit than in Phase 2 and immature survival data.

Terafab's GDP-Sized Ambition Starts With a Much Smaller Test
Musk says Terafab could rival a top-20 economy, but supplier talks, undefined output measures and a decade-long ramp make capital allocation the immediate issue for Tesla investors.
UPS Raises 2027 Rates, but the Average Hides Shipper Exposure
UPS will raise its U.S. daily rates for Ground, Air and international services by an average net 5.9% on December 21, extending a run of similarly sized annual increases. The headline does not tell customers what they will actually pay.
UPS says the effect will depend on a shipper’s service mix, package characteristics and contract terms. A customer sending lightweight parcels over short distances may experience a very different change from one shipping bulky packages into remote areas. Detailed rate previews had not yet been published when the increase was announced.
Several accompanying changes could matter more than the base-rate average. UPS will revise the ZIP codes subject to area surcharges and change the zones assigned to some ZIP codes. Zones are distance-based classifications used to determine shipping cost. The company will also increase the minimum billable weight for packages requiring additional handling from 40 pounds to 50 pounds.
That last change deserves careful interpretation. It does not mean every heavy package becomes cheaper or more expensive by the same amount. It changes the minimum weight used to calculate charges for packages that trigger the additional-handling rules, so the effect depends on the shipment’s actual and dimensional weight.
Small-business customers face a separate schedule. The source report said published small-business rates for Ground, Air and international services would rise 4.5%, alongside a 5% domestic and international fuel surcharge. UPS’s rate page confirms that small-business rates will increase on December 21, while the exact prices are available through the agreement-specific small-business page.
UPS is also preparing a per-package surge fee for certain Ground and Ground Saver shipments originating from specified ZIP codes for qualified customers. The company said the applicable locations and charges would be released in early November. That leaves some shippers unable to calculate their full 2027 exposure from the 5.9% figure alone.
For UPS investors, the increase supports revenue per package and helps offset labor, fuel and network costs. The tradeoff is demand elasticity: repeated increases encourage large customers to renegotiate, shift volume between carriers or redesign packaging. The source report noted that FedEx had announced its own 5.9% increase effective January 4, 2027, which reduces the risk that UPS is moving alone but does not eliminate customer resistance.
The most useful measure will be realized revenue per piece after discounts and mix, not the published average. Investors should also compare volume retention, surcharge revenue and margin performance once the new prices have been in effect for a full quarter.
USPS Adds a Weekly Fuel Surcharge to Package Shipping in 2027
The U.S. Postal Service will begin applying a weekly fuel surcharge to major domestic package services in January 2027, replacing part of its reliance on broad, temporary price increases with a charge that moves with energy markets.
The fee will apply to USPS Ground Advantage, Priority Mail, Priority Mail Express and Parcel Select. It will be calculated as a percentage of base postage and updated weekly using diesel and jet-fuel prices published by the U.S. Energy Information Administration. Negotiated service agreements may contain customized terms governing whether the surcharge applies.
Timing will vary by fuel type. USPS said diesel-based percentages will be published three to five days before implementation, while jet-fuel percentages will be available three to four days beforehand. Shippers will receive current and upcoming rates electronically, including through application programming interfaces, and historical data will be posted publicly.
The structure brings USPS closer to the pricing practices of UPS and FedEx, which already use fuel formulas that change with market prices. It also shifts more fuel-price risk to shippers. Customers will need systems that can ingest weekly rate updates, while merchants with fixed-price delivery promises may have to absorb short-term changes or revise checkout pricing more often.
The new mechanism follows an 8% temporary increase that USPS announced in March for the same four domestic competitive products. That adjustment took effect after regulatory review and is scheduled to remain in place through January 17, 2027. USPS described it as a bridge toward a permanent way to reflect transportation costs.
Pricing has already supported revenue even as package demand softened. The source report said USPS package-shipping revenue rose 7.7% from a year earlier in its fiscal third quarter while volume declined 3.4%. That combination shows the power of price, but it also highlights the risk that repeated increases can weigh on shipments. USPS still recorded a net loss in the quarter.
The surcharge is not a direct catalyst for a publicly traded USPS security because the Postal Service is an independent establishment of the U.S. government. For UPS and FedEx investors, the change narrows one pricing difference between the postal network and private carriers, but it does not by itself prove that competitive volumes or margins will change.
The practical questions are the initial surcharge percentages, how they interact with negotiated contracts and whether weekly adjustments alter customer behavior. Until USPS publishes those rates, shippers can prepare their systems but cannot calculate the full cost of the new policy.
Adobe’s Low Valuation Now Hinges on Converting Its AI Audience
Adobe’s business is still growing at a double-digit rate, but its shares are priced as if artificial intelligence will weaken the company’s creative-software franchise. The gap creates a clear test: Adobe must turn rapid growth in free and AI users into recurring revenue without giving up its unusually high margins.
Adobe reported fiscal third-quarter revenue of $6.76 billion, up 13% from a year earlier, and total annualized recurring revenue of $27.50 billion. Diluted earnings per share were $4.62 under GAAP and $6.13 on a non-GAAP basis. The company raised its full-year non-GAAP EPS target to $24.45 to $24.50 and guided fourth-quarter revenue to $6.80 billion to $6.85 billion.
The AI evidence is meaningful but not yet decisive. Adobe said AI-first ending ARR grew more than 150% year over year, while monthly active users across creativity and productivity products surpassed one billion. Creative freemium monthly users exceeded 100 million, up more than 70%, and Firefly ending ARR grew 40% from the previous quarter. Those measures show reach and early monetization, but they do not establish how efficiently free users convert into long-term paid customers.
That distinction explains much of the market’s caution. Adobe targets full-year ending ARR growth of 10.2%, slower than the growth rates attached to its newer AI products. It has deliberately emphasized audience expansion and postponed some planned pricing changes, sacrificing near-term net new ARR in the hope of building a larger funnel. Competition from Canva, Figma and new image and video models makes that conversion challenge more urgent.
The underlying cash generation remains strong. Adobe produced $2.52 billion of operating cash flow in the quarter and repurchased about 9.5 million shares. GAAP operating income was $2.35 billion, while non-GAAP operating income reached $2.97 billion. Management’s full-year target assumes a non-GAAP operating margin of about 45%, leaving room to fund AI development while continuing buybacks.
Valuation is the attraction, though the most aggressive claims require care. The source article cited a share price of $263.82 and a fiscal 2027 non-GAAP EPS estimate of $27.5076. Dividing those figures gives a forward multiple of about 9.6 times. That estimate is not company guidance, and the multiple will prove cheap only if earnings materialize. The same source said the shares were down about 24.6% in 2026, reflecting investor concern over AI competition, slower net new ARR and leadership change.
Anil Chakravarthy is scheduled to become chief executive on December 1, succeeding Shantanu Narayen, who will become executive chair. The leadership transition adds execution risk at the moment Adobe needs to show that freemium adoption can support paid growth.
The next useful evidence will be fourth-quarter revenue, ARR growth and operating margin, followed by conversion trends in fiscal 2027. If Adobe holds its margin while AI-first ARR becomes a larger part of the $27.5 billion recurring-revenue base, today’s valuation could understate the durability of the franchise. If conversion stalls, the low multiple may be a warning rather than an opportunity.
Google Cloud’s 82% Growth Narrows the Gap, but Not on a Clean Basis

Google Cloud’s second-quarter revenue rose 82% from a year earlier to $24.8 billion, a striking acceleration that strengthens Alphabet’s position in enterprise artificial intelligence. It does not, however, prove that Google Cloud will overtake Microsoft Azure within a year.
Alphabet said the growth came from AI infrastructure, AI solutions and core Google Cloud Platform services. The quarter also included the first revenue from TPU systems sold into customer data centers. Management said growth still accelerated materially when those system sales were excluded, but it did not quantify the adjustment.
Profitability improved alongside revenue. Google Cloud operating income more than tripled to $8.8 billion, lifting segment operating margin to 35.6% from 20.7% a year earlier. That combination matters because rapid infrastructure growth can destroy value if depreciation and capacity costs rise faster than revenue.
Demand is also visible in contracts. Google Cloud backlog reached about $514 billion, more than $50 billion higher than in the previous quarter. Alphabet expects to recognize just over half of that amount as revenue within 24 months. Management nevertheless said capacity remains constrained, which means the pace of data-center deployment can limit near-term sales.
The original analysis compared Google Cloud’s $24.8 billion of quarterly revenue with an estimated $29.4 billion for Azure and then projected each company’s latest growth rate forward for a year. That conclusion is too strong. Microsoft does not report Azure as a standalone revenue line, and Microsoft Cloud includes a broader collection of products than Azure. A one-quarter growth rate also cannot be assumed to persist, especially when Google Cloud’s comparison includes new TPU system sales.
The competitive direction is still important. Google Cloud grew much faster than Microsoft’s disclosed Azure growth rate and Amazon Web Services’ reported pace in the comparable period. But investors should compare like-for-like measures, margins and backlog rather than treat a simple revenue crossover as established fact.
Alphabet is paying heavily for that expansion. The source analysis cited second-quarter capital spending of $44.9 billion and negative free cash flow of $5.9 billion, while management raised its 2026 capital-spending outlook to $195 billion to $205 billion. Those figures make utilization and margin durability central to the investment case.
Alphabet and Microsoft are scheduled to report on October 28. For Alphabet, the decisive numbers are Google Cloud growth excluding unusual hardware contributions, operating margin and the pace at which backlog converts to revenue. If margin remains near the second quarter’s 35.6% while growth stays elevated, the cloud-share thesis strengthens. If margin contracts as outside capacity and depreciation increase, the revenue surge will be less valuable than the headline suggests.
Microsoft’s Cheap-Model Strategy Puts AI Margins to the Test

Microsoft CEO Satya Nadella expects the bulk of artificial-intelligence use to migrate toward cheaper, increasingly interchangeable models. For Microsoft, that forecast cuts both ways: lower inference costs can improve the economics of Copilot, while falling token prices can make the company’s enormous infrastructure buildout harder to monetize.
Nadella told the Possible podcast that companies should not use frontier models for non-frontier problems. He argued that most token consumption will eventually become a commodity market supplied by a mix of open-weight and lower-cost proprietary models. Microsoft already follows that approach inside Copilot, routing work to cheaper models when the task does not require the most capable system.
That matters because every answer generated by Copilot carries a computing cost. Microsoft can protect the margin on paid software seats by matching each request with the least expensive model that can do the job reliably. The company said on its fiscal fourth-quarter call that its in-house MAI models reduced GPU costs by 89% for one Dynamics 365 feature and by as much as 84% for a PowerPoint feature.
The pressure is visible in Microsoft’s accounts. Companywide gross margin declined from 69.8% in fiscal 2024 to 67.9% in fiscal 2026, while Microsoft Cloud gross margin fell to 65% in the June 2026 quarter from 68% nine months earlier. Operating expenses grew just 7% in fiscal 2026 as revenue rose 18%, so operating margin still expanded. Cheaper inference is one way to keep that favorable operating leverage as Copilot use grows.
The other side of the strategy is Azure. Microsoft sells the infrastructure that generates tokens, and a more competitive market can push prices down even as demand rises. Property and equipment additions reached $115.95 billion in fiscal 2026, up from $64.55 billion a year earlier. The asset base therefore needs high utilization and durable demand, not merely higher token volumes.
Microsoft has substantial contracted demand. Commercial remaining performance obligations reached $678 billion at June 30, 2026, up 84% from a year earlier and 25% excluding OpenAI. That backlog offers visibility, but it also shows why customer concentration and the economics of OpenAI-related commitments remain important.
The next test arrives with Microsoft’s fiscal first-quarter report on October 28. Management guided Microsoft Cloud gross margin to remain near 65%. Holding that level while AI usage expands would support the case that model routing and in-house systems are offsetting infrastructure costs. Another decline would suggest that pricing and depreciation are still moving faster than the savings.
Latest comments