


 Be The Investor Research
Crypto Theft Reached $1.18 Billion as Smart-Contract Losses Jumped
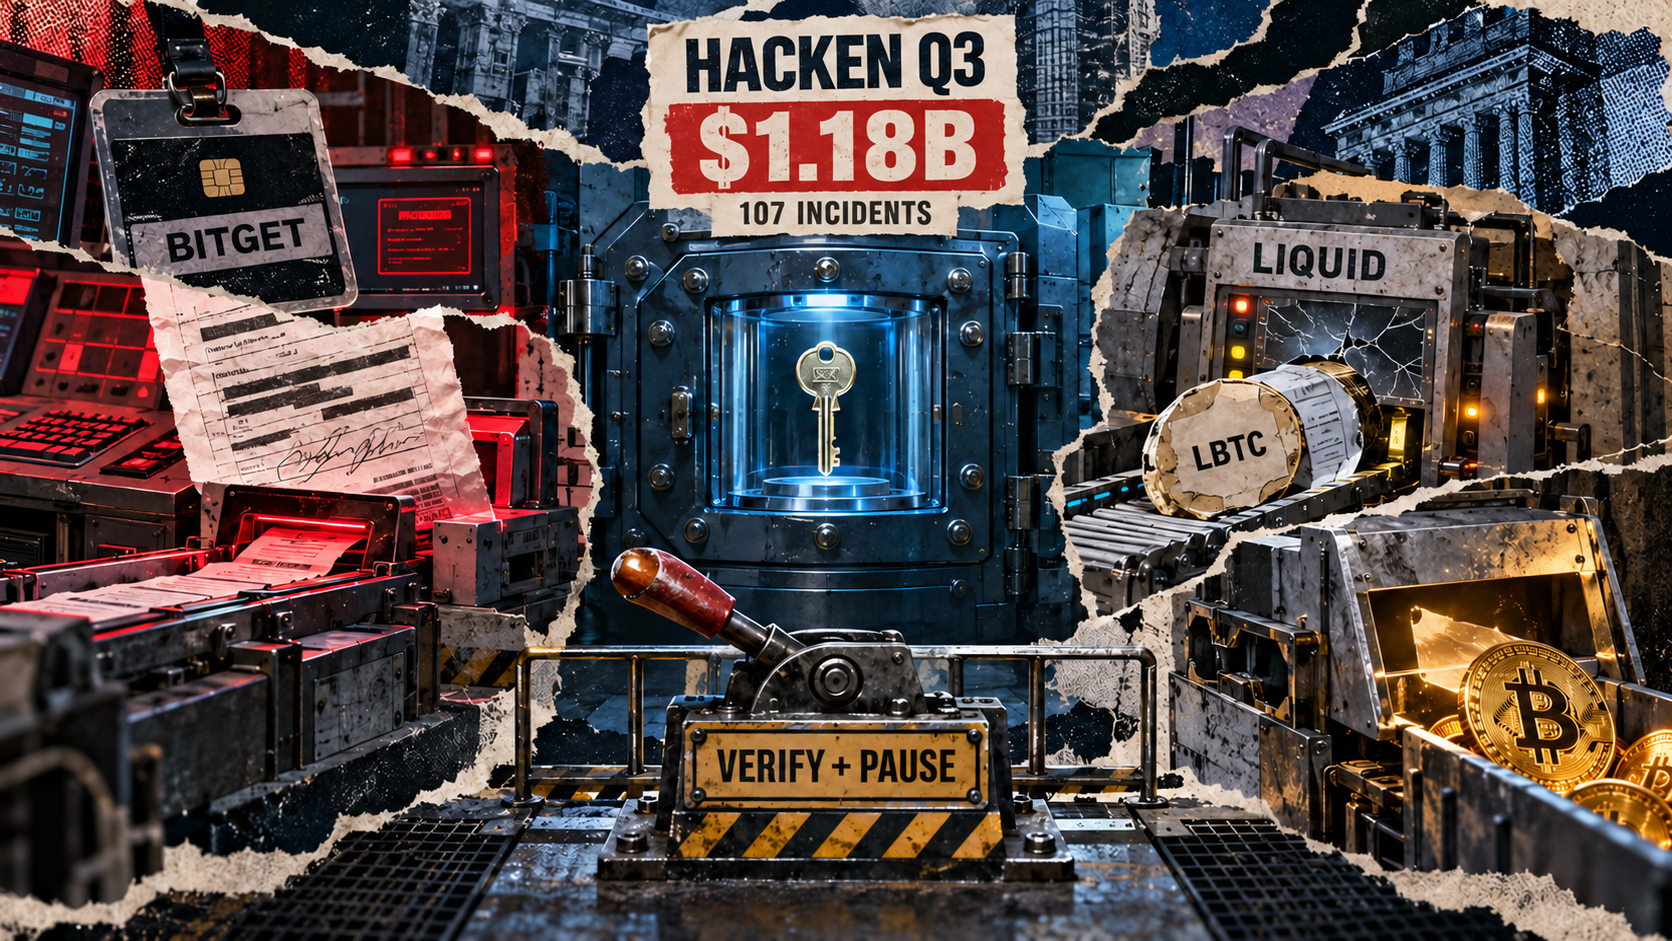
Hacken counted $1.18 billion stolen across 107 crypto incidents in the third quarter. Smart-contract exploits took a much larger share, showing why custody controls alone cannot contain platform risk.
Crypto theft reached $1.18 billion across 107 incidents in the third quarter, according to Hacken, up 55% from the second quarter. The increase came with a sharp change in the mix of losses: smart-contract exploits represented 48% of the total, compared with roughly 12% in the prior quarter.
The published totals imply an average recorded loss of about $11 million per incident in both periods. That calculation is only descriptive because a few large attacks can dominate a quarter, and Hacken's categories are broad. Still, it shows that the aggregate increase reflected more incidents and a different failure mix, not simply a higher average loss.
Two September cases illustrate the control problem. Bitget said attackers used compromised high-privilege credentials to inject unauthorized withdrawal instructions even though private keys were not stolen. In the Liquid incident, invalid assets passed a validation check before an automated process released genuine bitcoin. One failure occurred upstream of the signing key, while the other combined a validation defect with insufficient withdrawal friction.
The lesson for exchanges, custodians and investors is that no single control is enough. Key security, transaction authorization, smart-contract validation, withdrawal limits and manual escalation protect different parts of the path. Customer reimbursement can reduce user losses without proving the control failure has been fixed.
Quarterly categories should not become a checklist ranked only by last period's losses. The more useful test is whether independent controls can stop an asset transfer after an earlier safeguard fails.
Related News
Aave's Proposed USAT Gateway Adds Permission Risk to the Return Trip
Aave contributors proposed a permissioned Avalanche gateway between waUSAT and GHO. Users could transfer GHO freely, but recovering the deposited receipt token would require continuing approval and sufficient liquidity.
USDT Lost Exchange Balances as Stablecoin Rivals Paid for Distribution
Nineteen selected exchanges and lenders cut USDT balances by $4.6 billion in the third quarter while adding rival tokens. Tether retained a much larger payment footprint, separating trading incentives from adoption.
Bitcoin Funds Cut Net Shorts, but the Data Shows Less Risk, Not a Bull Turn
Leveraged funds reduced their net bearish CME bitcoin-futures position by nearly 15% through October 13. Rising spread trades and lower open interest point to de-risking rather than clear bullish conviction.
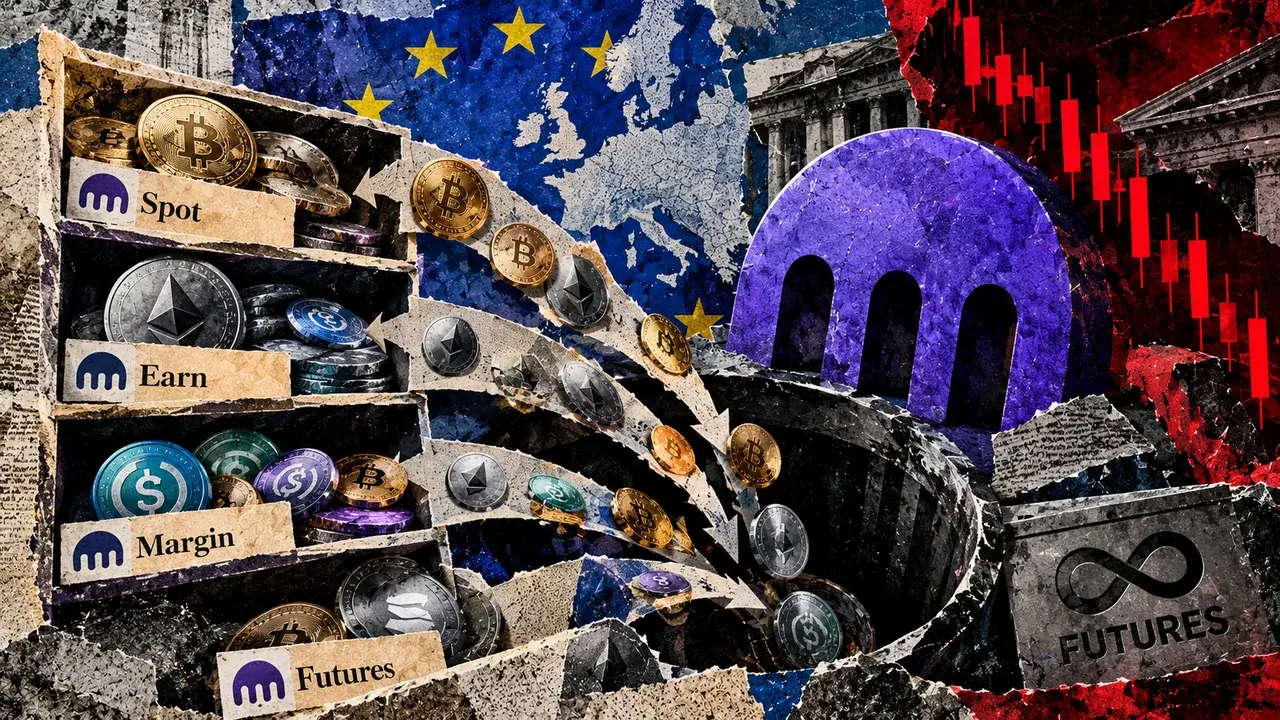
Kraken's Unified Wallet Makes Futures Losses a Broader Account Risk
Eligible European users can opt into Kraken's Unified Wallet and use spot and qualifying Earn balances as futures collateral. The convenience comes with a wider loss boundary under default cross margin.
Cardano's New Language Plan Meets a Much Harder Adoption Test
Charles Hoskinson is developing another Cardano programming language while the Leios upgrade advances. The technical work targets better execution, but Cardano's modest DeFi activity keeps commercial adoption central.
Strive Added 3,311 Bitcoin, but the Purchase Came With More Shares
Strive bought 3,311 bitcoin for about $280 million, lifting holdings to 32,773. The acquisition increased its treasury scale while new common and preferred shares highlighted the financing cost.
BitFuFu Mining Output Slipped as Ethiopia Deal Risk Moved Forward
BitFuFu produced 167 bitcoin in September, 4% fewer than in August, even as self-mining output rose to 98 bitcoin. The decline came from cloud mining, where output fell to 69 bitcoin, and from lower third-party computing capacity.
Managed hashrate fell to 19.4 exahashes per second from 20.6, while power capacity declined to 324 megawatts from 344. Self-owned hashrate stayed at 3.8 exahashes per second, making the reduction a reminder that BitFuFu's operating scale depends partly on suppliers and hosting customers it does not fully control.
The more important risk sits in Ethiopia. BitFuFu agreed in 2024 to acquire a majority stake in a company operating an 80-megawatt mining site. It has paid sellers $4.1 million and placed about 13,700 Antminer S19 machines there, representing roughly 1.57 exahashes per second and a reported net book value of $1.74 million.
The target is in a dispute with its power supplier, which threatened to seize collateralized equipment and assets if payment was not made. BitFuFu said it could terminate the deal, pursue arbitration and try to recover its payments and machines. Management described the exposure as a small part of total assets and said current production already reflects local curtailment.
September holdings still rose by 15 bitcoin to 1,388. That cushions the production decline, but it does not resolve the acquisition risk. Investors need evidence on ownership of the deployed machines, any recovery of the $4.1 million payment and whether the target's power contract remains viable.
Strategy Added 267 Bitcoin as Its Stock-Funded Treasury Expanded
Strategy bought 267 bitcoin for $22.1 million during the latest reported week, paying an average of about $82,900 per coin. The purchase lifted total holdings to 848,517 bitcoin at an aggregate reported average cost of $75,446.
The addition is small relative to Strategy's existing treasury, amounting to roughly 0.03% of its holdings. Its significance is therefore not a sudden change in bitcoin exposure. It is another example of the company's continuing capital-allocation model: issue securities or use cash, then add bitcoin while managing debt, preferred dividends and liquidity.
The company said the latest purchase was funded with proceeds from sales of Class A common stock. That matters to common shareholders because a treasury increase does not automatically increase bitcoin per share. The result depends on the number of shares issued, the sale price and the price paid for bitcoin.
Strategy also maintains separate dollar reserves and cash balances to support preferred dividends, interest and other obligations. Those resources reduce immediate liquidity pressure, but they sit alongside a complex capital structure whose claims must be considered before treating gross bitcoin holdings as common-equity value.
Bitcoin traded below Strategy's latest purchase price during parts of the week, illustrating the short-term volatility of the approach. The next useful disclosure is not simply another purchase total. Investors should compare changes in bitcoin holdings with fully diluted shares, preferred obligations and cash committed to buybacks or dividends.
USDY Passes BUIDL, but That Does Not Make ONDO Equity
Ondo Finance's USDY token has overtaken BlackRock's BUIDL in reported size, but that ranking says little about the value of ONDO. The source report put USDY at about $2.33 billion and BUIDL at about $2.2 billion on October 18, a narrow lead that one institutional allocation could reverse.
USDY gives holders economic exposure to a portfolio built around short-term U.S. Treasuries and bank deposits. Ondo says the token is not itself a Treasury security and gives holders no right to receive the underlying Treasuries. ONDO is different again: it is a governance token, not ownership in Ondo Finance, and has no direct claim on USDY reserves, fees or cash flow.
The source report estimated that 4.87 billion of ONDO's 10 billion maximum supply was circulating. A prior discussion about revenue-funded buybacks was only a temperature check, not a binding vote. BlackRock can also earn fees from products used in Ondo's reserve structure. The key question is whether ONDO ever gains an enforceable economic link to the business. Until then, USDY adoption and ONDO value can diverge.
Bitcoin's Quantum Risk Is Real but Not Imminent, Coinbase Says
Quantum computers do not pose an immediate threat to Bitcoin, but the network has a migration problem that becomes harder if users reuse addresses.
Coinbase Research estimates that roughly 6.51 million bitcoin, about 32.7% of supply at block 900,000, sit in output types whose public keys are already exposed. A sufficiently powerful quantum computer could, in theory, derive private keys from those public keys and authorize unauthorized spending.
That machine does not exist today. Coinbase noted that the most advanced systems have fewer than 1,000 qubits, far short of the scale required to break Bitcoin's cryptography. The near-term probability is therefore low, and no observed loss in the cited evidence was caused by a quantum attack.
Address reuse still matters because spending from an address reveals its public key. Older pay-to-public-key outputs, bare multisig and Taproot outputs can also expose keys in ways that create a long-range target. Every output may face a short window of vulnerability when its public key appears in the mempool during a spend.
Developers are considering paths such as BIP-360 and other quantum-resistant signature schemes. A migration would require years of standards work, wallet updates, node adoption and decisions about old coins. Larger post-quantum signatures could also raise storage, verification and fee costs.
For holders, the practical lesson is operational rather than predictive: avoid unnecessary address reuse and keep wallet software current. For the network, the challenge is to agree on a migration before quantum capability becomes urgent. Bitcoin's risk is not a present breach, but a slow coordination problem with a potentially severe endpoint.
Trump Media and Rumble Fell Faster Than the Market as Merger Risk Loomed
Trump Media fell 6% and Rumble dropped 8% during an October 16 market selloff, compared with a 1.4% decline in the S&P 500 proxy cited by the source. The gap is consistent with both stocks' smaller size and high sensitivity to changes in risk appetite, but the companies have different fundamental catalysts.
Trump Media's central event is its proposed all-stock merger with TAE Technologies. A September 30 SEC registration statement advances the approval process but remains preliminary. The filing says roughly 292.6 million new Trump Media shares are expected to be issued to TAE stakeholders based on then-current awards and warrants.
That share issuance would transform the company. TAE develops fusion energy, power management and cancer-therapy technology, while Trump Media operates Truth Social, streaming and financial brands. The merger could provide capital for TAE's development, but commercial fusion remains unproven and the transaction still requires approvals and completion conditions.
Rumble's exposure is more conventional. Its revenue depends on advertising, subscriptions, licensing and creator activity. A market selloff can pressure the shares, but its operating test is whether users, monetization and cash generation improve.
The one-day declines do not prove either business deteriorated that afternoon. They show how quickly valuation risk can surface when investors retreat from speculative equities. For DJT holders, the decisive evidence is the final merger terms, shareholder approval and the combined company's financing plan.
Latest comments