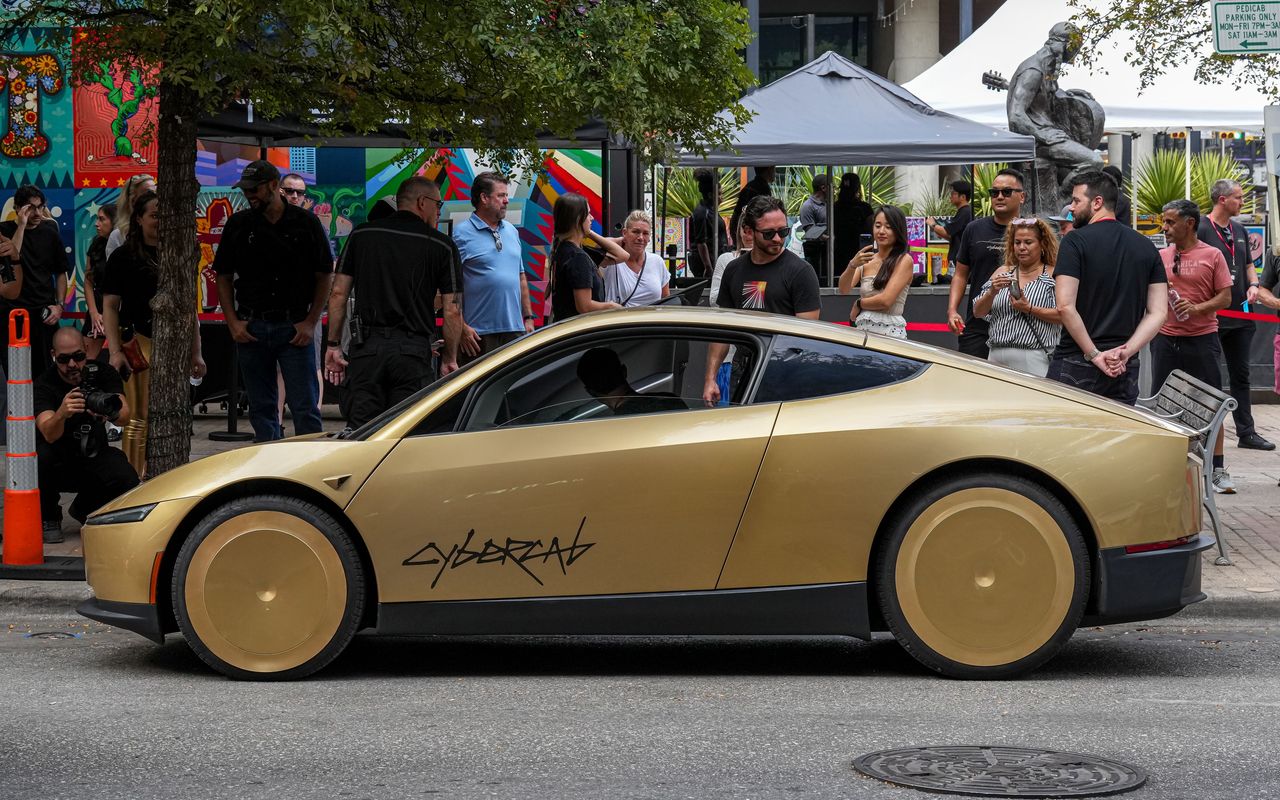
Tesla’s reported Cybercab fleet in Texas nearly doubled to 319 vehicles after 150 additional registrations, according to state records cited by investor Sawyer Merritt. The milestone matters because a larger fleet can accelerate data collection and operational testing. It does not yet establish commercial scale, regulatory clearance or attractive unit economics.
The distinction is important for Tesla shareholders. A registration count measures assets entering a fleet; it does not reveal paid rides, utilization, revenue per vehicle, insurance cost or remote-support expense. Those operating variables will determine whether Cybercab becomes a high-margin mobility network or a capital-intensive transportation business.
More vehicles, more learning capacity
The latest registration batch lifted the reported total from 169 to 319 and was the largest single-day increase since Cybercab first appeared in the Texas registry on August 31. Austin remains the only public market identified in the report.
At this scale, each incremental vehicle can contribute route data and expose edge cases that a small pilot may miss. But the fleet is still tiny relative to the volume required for a nationwide ride-hailing platform. Investors should therefore treat the jump as evidence of deployment progress, not as a proxy for market share.
Tesla’s broader software base provides a potential data and distribution advantage. Its [second-quarter operational summary](https://ir.tesla.com/_flysystem/s3/sec/000162828026049213/tsla-20260722-gen.pdf) reported 1.48 million active Full Self-Driving subscriptions. Yet FSD Supervised requires driver attention, while a pedal-free Cybercab is a different regulatory and liability proposition. Tesla also does not separately disclose FSD revenue, limiting any attempt to translate subscriber growth into robotaxi economics.
The federal inquiry is the nearer catalyst
The National Highway Traffic Safety Administration opened an Audit Query on September 4 into Tesla’s self-certification of the Cybercab. The agency is asking how the vehicle complies with federal motor-vehicle safety standards, including a braking rule written around a foot control. According to the report, NHTSA granted Tesla an extension to October 30—shorter than the November 20 deadline Tesla requested—and required sworn responses to 21 information requests.
That process does not mean NHTSA has found the vehicle unsafe. It does mean the path from Texas registrations to wider deployment depends on a technical and legal record that investors have not yet seen. A satisfactory response could reduce one uncertainty; a demand for design changes or additional evidence could slow production and add cost.
Five growth stories, one valuation problem
Tigress Financial’s bullish case spans FSD subscriptions, Cybercab, Optimus robots, energy infrastructure and opportunities involving SpaceX. The diversification is appealing, but it can also obscure which businesses are producing cash today.
Tesla delivered more than 480,000 vehicles and deployed 13.5 GWh of energy-storage products in the second quarter, according to its [July production release](https://ir.tesla.com/press-release/tesla-second-quarter-2026-production-deliveries-and-deployments). The source article also reported $3.14 billion of quarterly energy revenue, $318 million of revenue from SpaceX Megapack purchases and a $2 billion minority investment in SpaceX. Those figures show that Tesla is already committing capital across several ambitious programs.
Cybercab should be judged separately. A useful disclosure set would include paid-trip growth, autonomous miles between interventions, fleet utilization, revenue per mile, insurance losses, remote-operator staffing and vehicle depreciation. Without those numbers, a higher registration count improves the evidence of physical rollout but not the evidence of profitability.
Insurance data may eventually provide an external signal. Lemonade expanded discounted coverage to additional Tesla hardware and FSD software combinations in three states, offering a 30% saving on eligible supervised miles and 50% for newer configurations. Those discounts do not prove that an unsupervised Cybercab is safe, but they show how driving telemetry could influence pricing. For robotaxis, the relevant comparison will be total loss cost per autonomous mile, not the discount attached to supervised consumer driving.
Scale can also cut two ways. More cars spread mapping, dispatch and remote-support systems across a larger revenue base, but low utilization leaves Tesla carrying depreciation and financing expense on idle vehicles. Paid-trip and utilization disclosures would reveal which effect dominates.
The next decisive event is Tesla’s October 30 response to NHTSA. If the company clears the certification questions and begins reporting real operating metrics, Cybercab can move from a fleet-count story toward an investable business case. Until then, 319 registrations are a promising input—not the output investors ultimately need.