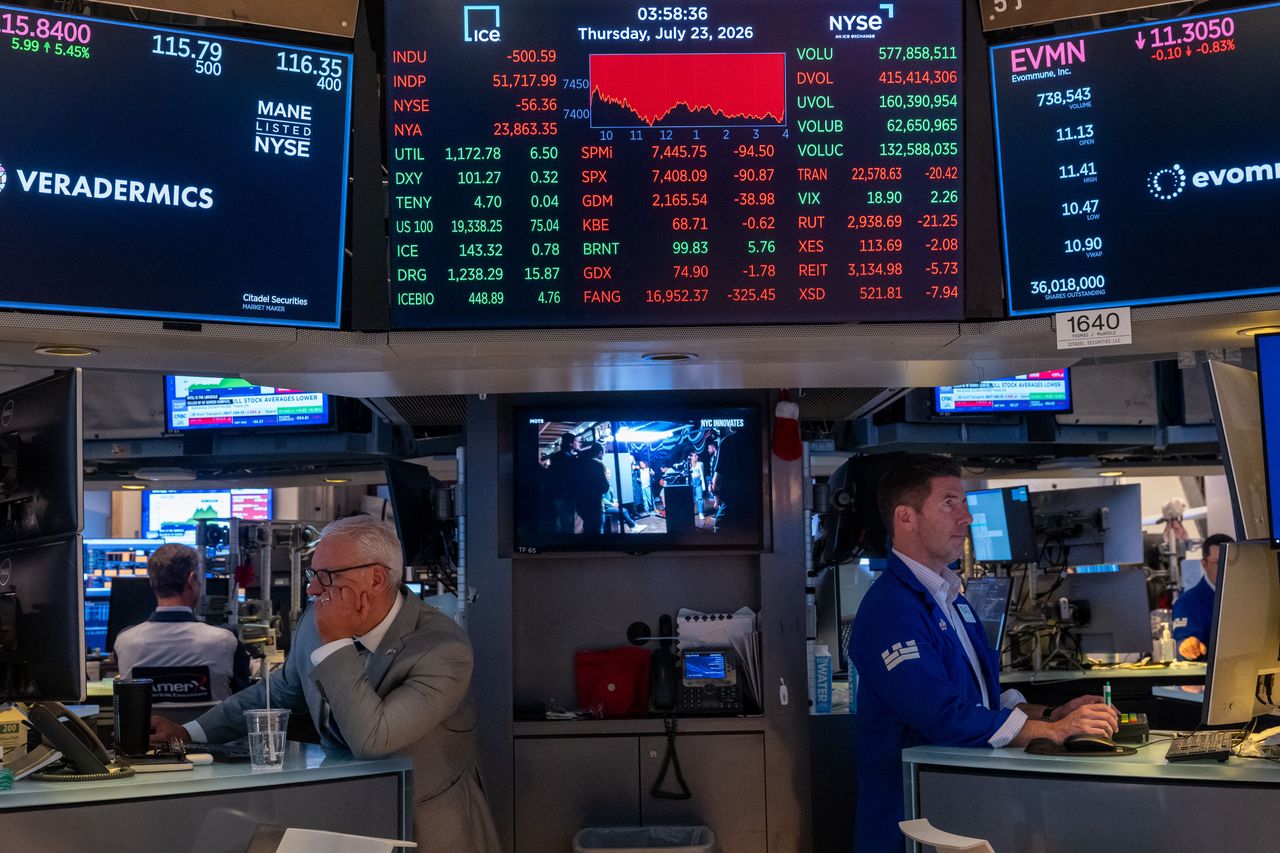
U.S. equities slipped from record territory as long-term Treasury yields moved to levels not seen in decades, creating a valuation shock that was broader than any single company's earnings news. The S&P 500 and Nasdaq-100 each fell about 0.2% on October 7, while the Dow declined 0.7% and the Russell 2000 lost roughly 1%. Semiconductor ETFs fell about 1%, reflecting the rate sensitivity of long-duration growth assets.
Federal Reserve H.15 data released October 7 showed the 10-year Treasury constant-maturity yield at 5.27% and the 30-year yield at 5.64% for the latest official observation. Intraday market quotes cited by Stocktwits were higher, at 5.365% and 5.732%, respectively. The difference is methodological and timing-related: official daily constant-maturity values should not be mixed with an intraday high as if they were the same measurement.
Why yields matter for equities
A higher risk-free rate reduces the present value of future cash flows and raises the return investors can earn without taking equity risk. That pressure is greatest for companies whose valuations depend heavily on profits expected far in the future. Semiconductors and AI-linked stocks can still grow rapidly, but the multiple investors are willing to pay for that growth may fall when Treasury yields rise.
Small caps face an additional channel. Many smaller companies depend more on floating-rate or near-term refinancing and have less diversified funding. The Russell 2000's larger decline was therefore consistent with both valuation pressure and higher prospective interest expense.
The market move was not a verdict on AI demand
Nvidia, AMD and Marvell weakened, but the session also included reports of large financing demand for AI chips. That combination shows the distinction between operating demand and valuation: a company can retain strong end-market demand while its stock falls because the discount rate rises.
Bond demand provided some stabilization after a Treasury auction, and yields pulled back from session highs. The next test is whether the move reflects a temporary positioning adjustment or a persistent repricing of inflation, growth and Federal Reserve policy. Investors should compare real yields, inflation expectations and auction demand rather than focus only on a round-number nominal yield.
Sector dispersion offers another diagnostic. Banks can benefit from higher yields only if deposit costs, credit losses and curve shape cooperate; utilities and real estate often suffer because debt costs rise and bond alternatives become more attractive. Energy and commodity shares may respond more to inflation expectations than to the nominal rate alone. A broad selloff with these internal differences is more consistent with discount-rate repricing than with a single earnings shock.
Near record highs, even a modest rise in required returns can pressure richly valued sectors. If yields remain elevated, earnings growth must do more work to support prices; if yields retreat, the same long-duration sectors could rebound quickly. The session was primarily a cost-of-capital event, not evidence that the technology earnings cycle had suddenly broken.